By Tony Fiddis: China Analyst.
What Is Project mBridge, and Why Does It Threaten Dollar Dominance?
For years, the financial world has operated on a foundational, almost unshakeable assumption: the United States dollar is the ultimate bedrock of global trade. Washington prints the reserve currency, monitors transactions routed through SWIFT, and wields sanctions like economic precision-guided munitions. But behind closed doors, central banks around the globe have spent years quietly exploring an exit ramp.
Chief among these initiatives was Project mBridge—a sophisticated, multi-central bank digital currency (mCBDC) platform backed heavily by Beijing. The vision was audacious: construct a frictionless, blockchain-powered financial pipeline capable of settling international transactions directly between central banks, bypassing Western intermediary clearing banks and sidestepping the US dollar entirely.
Yet, this ambitious blueprint has just run headfirst into cold, hard geopolitical reality. Saudi Arabia, one of the project’s most strategically vital energy players, has officially stepped back from mBridge. While Riyadh insists the move is simply the natural conclusion of a technical trial, the ripple effects reveal a much deeper, more fractured landscape in the fight for the future of global money.
Why Does This Move Threaten Dollar Dominance?
To fully understand why Saudi Arabia’s pivot matters, you first have to understand the sheer disruptive potential of mBridge itself.
Modern cross-border payments are surprisingly archaic. When funds move between disparate nations, they typically crawl through a fragmented web of correspondent commercial banks, layered across multiple time zones, currencies, and regulatory checks. Most of these flows ultimately route through dollar-denominated accounts and the SWIFT messaging network. This infrastructure is not only slow and expensive; it grants Washington near-total visibility and jurisdictional leverage over global commerce.
Conventional Correspondent Banking vs. mBridge Model:

[Bank A] ──> [Intermediary US Bank] ──(SWIFT / USD Clearing)──> [Intermediary Bank] ──> [Bank B]
                                vs.
[Central Bank A (CBDC)] ═══════════ (mBridge Ledger) ═══════════> [Central Bank B (CBDC)]
mBridge cuts this Gordian knot by creating a shared distributed ledger. Central banks issue their own Central Bank Digital Currencies (CBDCs) and swap value peer-to-peer in real time.
Key Technical Advantages of mBridge
Near-Instant Settlement: Collapsing cross-border clearance times from days to seconds.
Radical Cost Reduction: Slashing foreign exchange friction and correspondent banking fees.
Sanction-Resistant Architecture: Operating independently of Western financial chokepoints and the US dollar.
In theory, if major oil exporters and heavy industrial importers settled commodities on mBridge, the petrodollar could face its most credible systemic challenge since Bretton Woods.
The Saudi Exit: Strategic Realism Over Ideology
When the Saudi Central Bank (SAMA) formally joined mBridge in 2024 alongside the central banks of China, Hong Kong, Thailand, the United Arab Emirates (UAE), and the Bank for International Settlements (BIS), the move sent shockwaves through Washington. As the anchor of the petrodollar system, Saudi participation lent Beijing’s alternative settlement system immense institutional credibility.
That credibility has now suffered a severe blow.
The Saudi Central Bank confirmed that its active proof-of-concept phase concluded in May 2025, clarifying that it is no longer a participating member of the platform. Officially, Riyadh frames this departure as routine project governance, firmly denying that the decision reflects any geopolitical realignment or cooling ties with Beijing.
mBridge Participant Timeline:

2024:
├── Saudi Arabia joins China, HK, Thailand, UAE & BIS
└── October: Bank for International Settlements (BIS) departs under US scrutiny

2025:
├── May: Saudi Central Bank concludes trial and steps back
└── June: Macau formally joins the platform for launch deployment
Yet international finance rarely happens in a vacuum. Riyadh's departure follows an identical precedent set by the Bank for International Settlements itself, which withdrew from mBridge in October 2024 amid intense scrutiny from US lawmakers. For Saudi Arabia, holding the door open to Beijing while jeopardising its vital security, defence, and investment partnerships with the United States was simply a bridge too far.
Washington's Counterattack and the New Currency Cold War
Riyadh's calculated retreat underscores a primary obstacle facing alternative clearing networks: the US dollar's dominance is defended not just by economic inertia but by active political power.
Washington has watched mBridge evolve with mounting alarm. A functional, high-volume alternative to SWIFT does not merely dilute the dollar’s global footprint; it fundamentally disarms US foreign policy. If designated foreign entities can trade energy, commodities, and industrial goods via sovereign digital tokens on an encrypted, distributed ledger, the enforcement of unilateral economic sanctions becomes virtually impossible.
The Rising Cost of Challenging the Greenback
The geopolitical stakes around de-dollarisation have escalated sharply:
Sanctions Integrity: Western regulators see bilateral CBDC corridors as bespoke sanctions-evasion channels built right under the global financial system.
Tariff Retaliation: Donald Trump explicitly threatened nations within the BRICS orbit with 100% punitive tariffs should they attempt to undermine or replace the dollar in international settlements.
Diplomatic Leverage: Developing nations attempting to hedge between the East and the West find their room to manoeuvre shrinking rapidly.
For Riyadh, the calculus was clear: the marginal cost savings of a blockchain settlement network were radically outweighed by the threat of alienating American trade and security architecture.
Beijing’s Dilemma: Commercial Viability vs. Global Pushback
Is Project mBridge finished? Far from it.
The initiative continues to march toward broader commercial deployment. The Monetary Authority of Macao formally joined the platform, launching the system into operational phases alongside the central banks of China and the UAE. Cross-border pilot flows continue, and the underlying technological architecture has proven that multi-currency atomic swaps can function at scale.
Current Status of the mBridge Platform:

[Active Anchors]
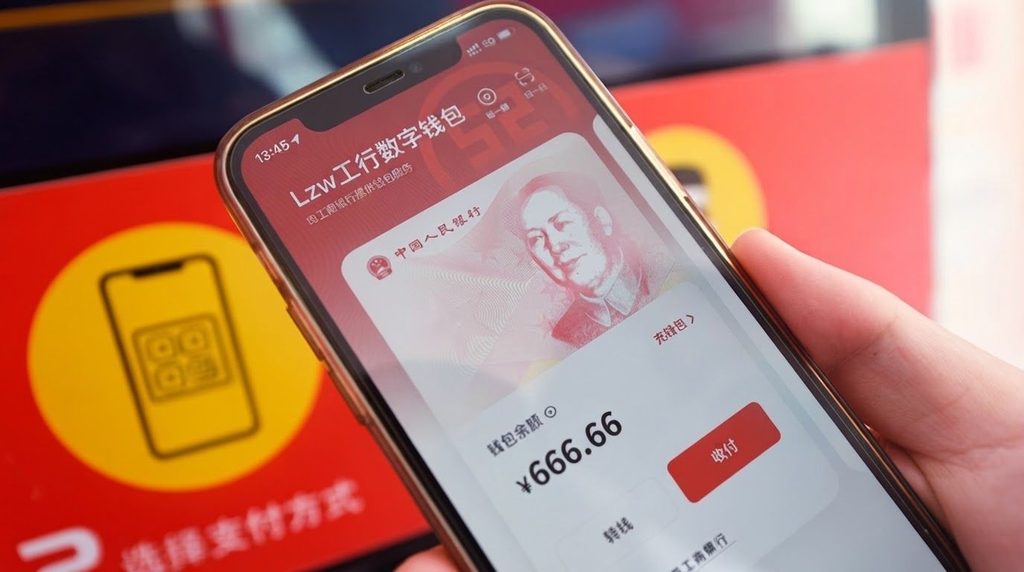
├── People's Bank of China (Digital Yuan / e-CNY)
├── Hong Kong Monetary Authority
├── Bank of Thailand
├── Central Bank of the UAE
└── Monetary Authority of Macao (Joined mid-2025)

[Key Departures]
├── Bank for International Settlements (BIS) - Departed Oct 2024
└── Saudi Central Bank (SAMA) - Concluded participation May 2025
However, mBridge’s core obstacle was never purely engineering; it is systemic trust. China is attempting to forge technological and financial independence, lift the cross-border role of the digital yuan, and challenge the dollar’s hegemony while grappling with serious domestic economic headwinds.
Building an alternative financial system requires global counterparties to trust the platform's neutrality. As Beijing’s international relationships face mounting friction, potential partners are realising that adopting Chinese-backed rails brings geopolitical baggage they cannot afford.
The Illusion of Financial Neutrality
Saudi Arabia’s quiet exit from mBridge is a clarifying moment in the evolving digital currency landscape. It demonstrates that you cannot divorce financial plumbing from global geopolitics.
Emerging economies genuinely want the efficiency, speed, and diversification that multi-CBDC rails provide. What they do not want, however, is to be forced into picking a side in a zero-sum economic standoff between the world’s two largest superpowers.
Project mBridge has demonstrated that a post-dollar, blockchain-enabled financial architecture is technically viable. But as Saudi Arabia just proved, until a digital settlement network can shield its participants from the brutal realities of geopolitical retaliation, the US dollar will remain the default currency of global trade—not necessarily because it is the most modern, but because the alternatives simply carry too high a price.